Can the “8.28 New Policy” Bring a “Second Spring” to the Real Estate Bond Market? — The 30th (Shanghai) Investor-Financier Exchange Meeting of Anrong Credit Rating Successfully Held
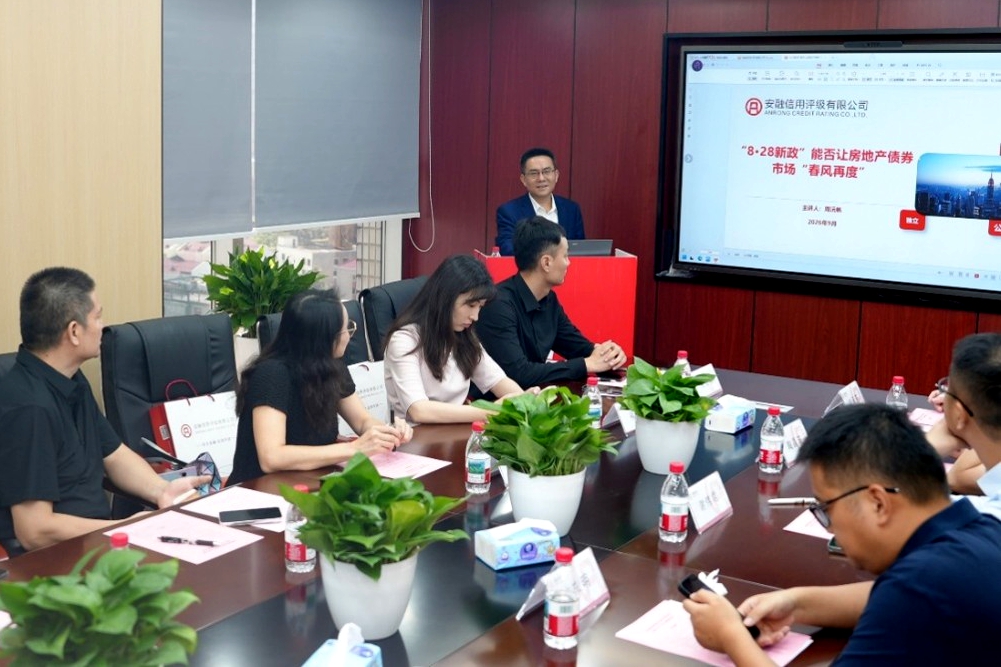
On September 12, the 30th (Shanghai) Investor-Financier Exchange Meeting of Anrong Credit Rating Co., Ltd., centred on the theme “Can the ‘8·28 New Policy’ Bring a ‘Second Spring’ to the Real Estate Bond Market?”, was held in Shanghai. Anrong Credit Rating joined representatives from more than 50 partner financial institutions, academic institutions, and clients—including TF Securities, Guosen Securities, Zhongtai International, Fosun United Health Insurance, Zheshang Leasing, Guidun Investment, Qinwen Investment, Xiamen International Bank, East Asia Qianhai Securities, Jiang Mianfeng Private Fund, Anhong Investment, Shanghai Iron King Kong Industrial Development Group, and Shanghai Sendun Investment Management—at the company’s new Shanghai headquarters. Participants held in-depth discussions on topics including the institutional implications of the “8·28 New Policy,” the current state of the real estate sector, and the evolving opportunities and risks in the real estate bond market.
First, Dr Zhou Yuanfan, Chief Economist of Anrong Credit Rating, delivered a presentation titled “Can the ‘8·28 New Policy’ Bring a ‘Second Spring’ to the Real Estate Bond Market?” and engaged in frequent, in-depth exchanges with attendees. Dr Zhou noted that, unlike the short-term “firefighting” stimulus policies of the past, the “8·28 New Policy” represents a systematic restructuring of the real estate sector’s foundational institutions. It addresses institutional shortcomings in three areas—housing sales mechanisms, credit management, and capital market support—by introducing measures such as reforms to completed-home sales, a lead-bank system for development loans, extensions of individual mortgage loan terms, and broader applications of REITs and asset securitisation tools. These measures aim to close loopholes in the previous model, including highly leveraged land acquisition, risks associated with presale funds, and overlapping credit extensions and loan withdrawals, while opening new avenues for development in rental housing, urban renewal, mergers and acquisitions, and revitalising existing assets.
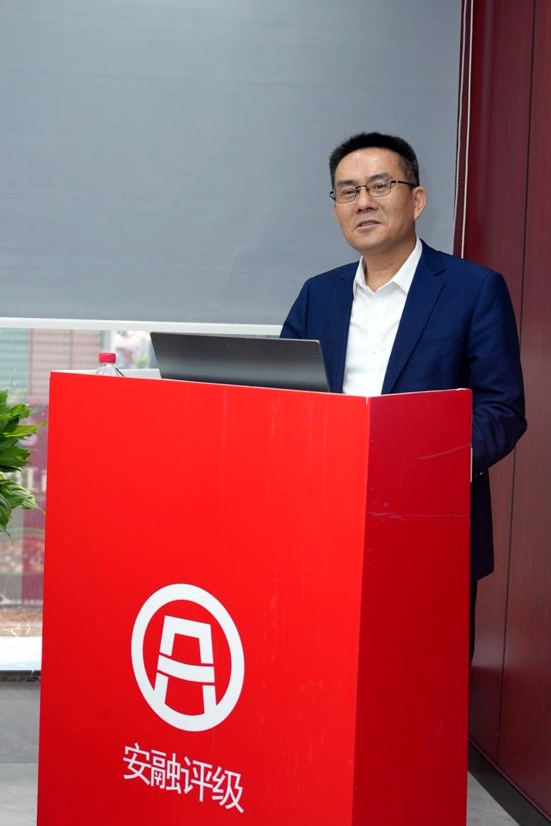
Dr Zhou reviewed the current state of the real estate and real estate bond markets. The industry has entered an era of existing housing stock, with the proportion of second-hand home transactions continuing to rise, while key indicators such as investment, construction starts, and sales remain in an adjustment phase. After several rounds of risk releases, defaults in real estate bonds have gradually declined; however, market differentiation remains pronounced. Bond issuance is currently highly concentrated among central and state-owned enterprises, private real estate developers account for a relatively low proportion of financing, and financing costs vary significantly among issuers. He outlined three scenarios for the future trajectory of real estate bonds: under an optimistic scenario, simultaneous improvements in financing, cash collections, and repayment capacity would drive an overall market recovery; under a cautious scenario, weak sales and pressure from outstanding debt would constrain the extent of recovery; and under a neutral scenario—the most likely outcome—the market would show structural differentiation, with high-quality projects and issuers improving first while weaker entities continue to exit. For policy benefits to translate into bond repayment capacity, practical obstacles such as closed management of project funds and upstream transfers of group funds must still be overcome. Policy issuance should not be simply equated with credit recovery; actual receipt of financing, realization of project cash collections, and improved debt repayment should serve as the key signals of a market rebound.
During the roundtable discussion, participants shared their views on market hot topics including the implementation effects of the new policy, debt resolution pathways for real estate developers, investment screening logic for real estate bonds, approaches to revitalising existing assets, and risk-identification indicators. Participants generally agreed that the “8·28 New Policy” establishes an institutional framework for the industry’s long-term healthy operation and will help restore market expectations. However, it will take time for the real estate bond market to experience a broad-based “spring.” Industry recovery remains highly dependent on a rebound in commercial housing sales and sustained improvements in project cash flows. On the investment side, investors should continue to distinguish project quality, assess issuer creditworthiness, and view policy benefits rationally.
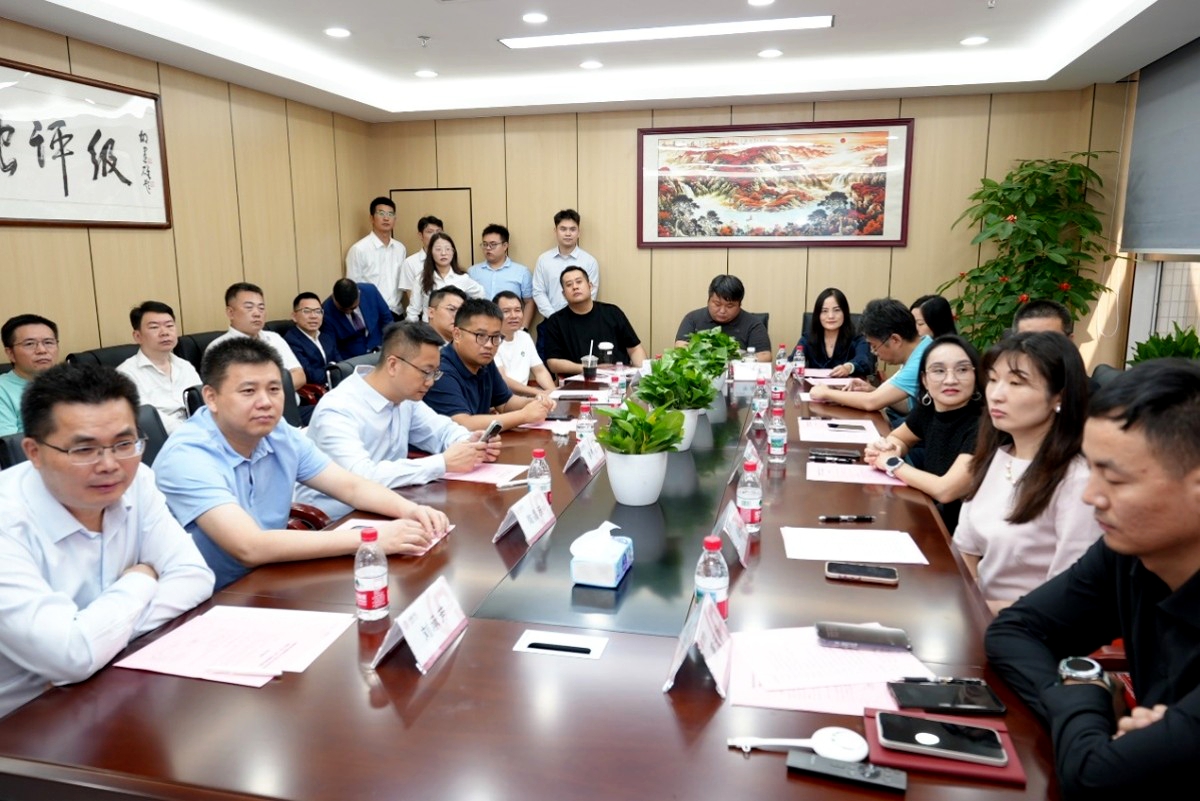
Based on broader industry trends, this exchange meeting focused on key pain points in the bond market and assessed developments after policy implementation. It delivered value through policy interpretation, market review, risk assessment, and idea exchange, while providing an efficient platform for communication and collaboration among institutional investors, financial practitioners, and real-economy enterprises. Going forward, Anrong Credit Rating will continue to deepen its credit research, closely monitor policy iterations in the real estate sector and changes in bond market cycles, regularly organize investor-financier exchange and research activities, and continuously provide professional market analysis. These efforts will help market participants grasp industry trends, make sound investment and financing decisions, and support the stable and healthy operation of the bond market as well as the high-quality development of the real economy.